Financial Advisors & Wealth Managers

You advise on what clients disclose. Families inherit everything else.

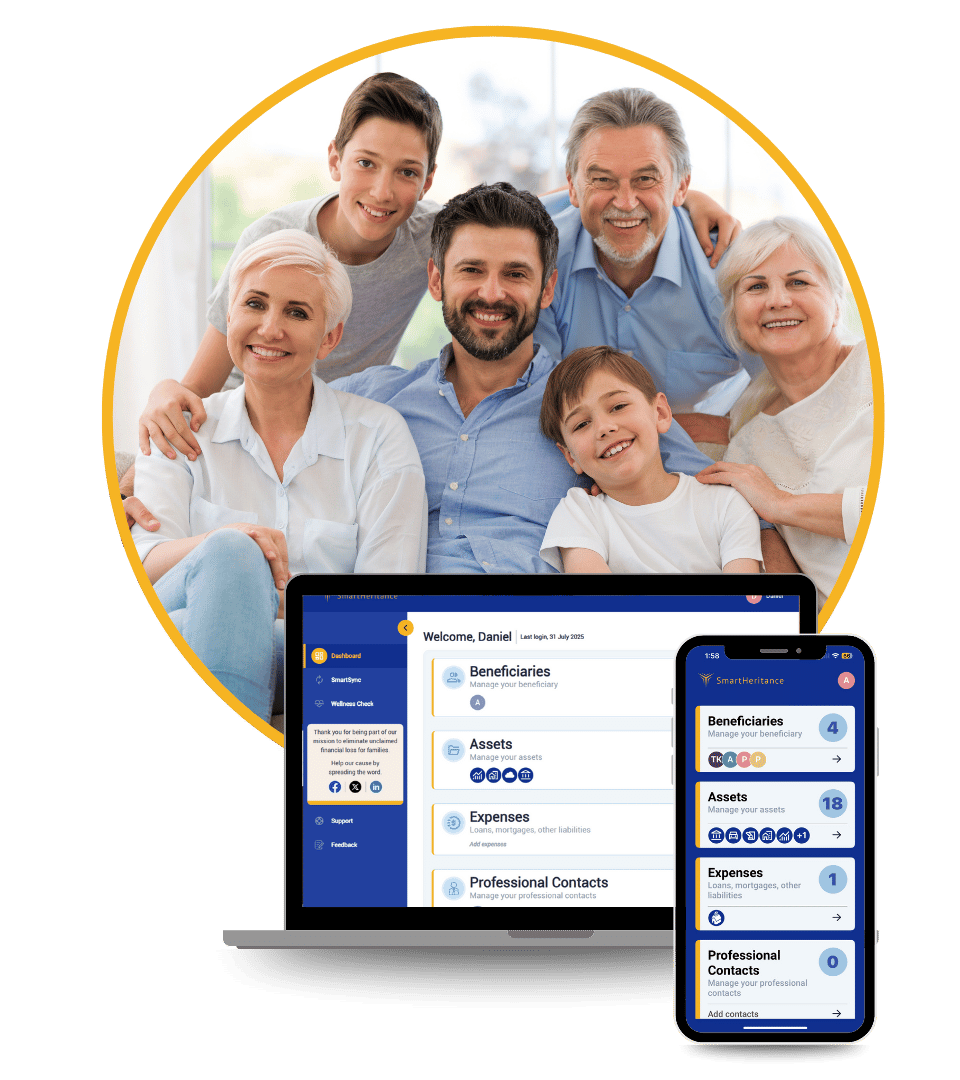
Most clients hold accounts you are never told about, and their records describe a financial life they have already outgrown. SmartHeritance gives financial advisors and wealth managers a complete client asset inventory, then puts your practice in front of the family before the estate moves.

The SmartHeritance record
SOC 2 Type II Certified· Bank-Grade Encryption· Zero-Knowledge Architecture· Client-Controlled Disclosure· No Custodian Or CRM Integration· Deploys In Days
The Visibility Gap

Your client's entire financial life, in one place.

The portfolio you manage is a fragment of the financial life you are asked to advise on. The family that inherits it has never met you.

A Typical Affluent Household

Visible to you

Managed portfolioIRAJoint account

The portfolio under your management

Held elsewhere

Second advisorLegacy 401(k)Old brokerage

Undocumented

Life policyProperty deedDigital holdings
01

Clients do not disclose everything at once.

Affluent households distribute assets across two or three firms until an advisor has earned several years of trust. Plans are built on a partial balance sheet.

Held-away assets remain the largest untapped source of organic growth in most practices

02

Records go stale between reviews.

A client opens a brokerage account, refinances a property, or acquires digital assets in March. The documents still describe their circumstances from four years ago.

$77B+ in unclaimed assets in the US: a documentation failure, not an absence of wealth

03

When the estate moves, the relationship rarely survives it.

By the time a practice learns a client has died, the heirs have already appointed someone else. Assets leave in the transfer more often than in a downturn.

More than 70% of heirs change or drop their parents' advisor after inheriting

The question is not whether a practice can organise a client's paperwork. It is whether it will still be managing the assets in ten years, and whether it ever saw all of them.

$124T

Passes between generations in the US through 2048. Every dollar places an advisory relationship back in play.

>70%

Of heirs are likely to change or drop their parents' financial advisor once they inherit.

$54T

Moves to a surviving spouse first. Nearly $40T of it goes to widowed women, most of whom were never in the room.

Source: Cerulli Associates, U.S. High-Net-Worth and Ultra-High-Net-Worth Markets.

How It Works

Four steps. No integration at any of them.

The platform does the collecting and the maintaining. Your practice sends one link and reads what the client chooses to share.

1

Clients are invited through a branded link

No procurement and no IT project. We provision a sign-up link carrying your firm's name; you send it alongside the next review agenda. Clients verify by OTP.

Advisor effort: one email
Illustration: invitation envelope with gold key
2

The vault collects and structures what exists

Accounts, policies, deeds, digital holdings and instructions are located and organised, including those held away from you. SmartSync maintains the record as circumstances change.

Nothing is created. Everything is located and organised
Illustration: documents drawn into a vault
3

Material changes surface to you

A new account, a lapsing policy, a revised beneficiary. Each update is a substantive reason to make contact, where the client has granted visibility and only for as long as they maintain it.

Visibility granted by the client, revocable by the client
Illustration: alert bell over a rising chart
4

The family is named well in advance

Clients designate who receives what, and under which predefined conditions. When the transfer arrives, the heirs are already known to you, and you to them.

The retention step, years before it is needed
Illustration: three-generation family group
Practice Value

What changes about your book.

🎯

The complete balance sheet becomes visible

Clients record what they hold everywhere, not only what sits with you. Advice improves, and so does the conversation about consolidation.

Organic growth from assets already in the family

📈

Retention through the transfer, not up to it

Heirs and trusted contacts are designated during the client's lifetime, so the introduction happens years before an estate is redistributed.

Assets that survive the generational handover

🔗

Contact grounded in substance

Every material change in a client's records is a relevant, specific reason to speak. Engagement stops depending on quarterly returns.

Sustained engagement clients welcome

💡

Fewer disputes, faster settlement

Accurate, current records remove the ambiguity that turns an estate into a family argument, and shorten the administration a practice is drawn into.

Less time in administration, more in advice

⚡

A capability your custodian does not provide

Family continuity is an emerging category. Offering it now distinguishes a practice from every firm still circulating an annual PDF checklist.

Differentiation against table-stakes tools

🤝

Nothing to build and nothing to unwind

No integration, no assets custodied, no advice provided by us. A pilot requires a link and an announcement, not a vendor review.

Assessable within one review cycle

The Industry Position

The largest practices already treat this as retention work.

Multigenerational engagement is not run as a differentiator at the top of the market. It is run as the mechanism that keeps assets in the firm.

Source: Cerulli Associates.

Leading HNW firms prioritising family meetings and generational planning

89%

Rate family communication their most effective transfer strategy

81%

Inherited annually in the US, rising through the next decade

$2.5T TODAY
$3T+ 2030
$4T+ MID-2030s
What You Get Visibility Into

A digital asset vault that aggregates what already exists.

SmartHeritance does not draft documents, write policies or provide advice. It locates the records a household already holds, structures them, and keeps them current, so the knowledge that matters to a financial decision finally sits in one place and stays legible to you where the client permits it.

Nothing here is generated by the platform. Every item is an existing account, policy, deed or instruction that is collected, organised and maintained.
Illustration: magnifier over aggregated statements
🏦

Financial

  • Bank and brokerage accounts
  • Retirement plans held elsewhere
  • Mortgages and outstanding loans
  • Safe deposit boxes

Reveals held-away assets

📋

Insurance and legal

  • Life and disability policies
  • Property and casualty coverage
  • Wills, trusts and deeds
  • Carrier and counsel contacts

Surfaces coverage gaps and lapses

🔐

Digital holdings

  • Digital currency positions
  • Online financial accounts
  • Recurring obligations
  • Access and recovery records

Captures value outside custody

💌

People and intent

  • Designated heirs and contacts
  • Release conditions
  • Existing advisors and counsel
  • Final instructions

Introduces you to the next generation

Implementation

Begin with a defined pilot, not a procurement cycle.

A single cohort of clients, a fixed period, and measurement on adoption and record completeness. Nothing to integrate and nothing to unwind if the practice decides against it.

The first cohort is offered at no cost to the practice. Commercial terms are scoped once the pilot data is reviewed.

No integration with your custodian, CRM or planning software

No assets custodied, no transactions executed, no advice provided by us

Visibility granted by the client, revocable by the client

White-label options for RIAs, credit unions and community institutions

Compliance documentation provided on request

1

Select the pilot cohort

Twenty to fifty households, typically those nearest a transfer or those suspected of holding assets elsewhere.

2

We provision and brand the link

Your firm's name on the invitation. We supply the announcement copy and the client-facing explainer.

3

Clients onboard themselves

OTP verification and guided setup. No advisor time is required beyond sending the invitation.

4

We review the results together

Enrolment, record completeness and engagement at the close of the pilot. The practice decides what follows.

Privacy and Compliance

The client owns the record. Always.

What a client records is deeply personal. Access is granted by the client. It is never assumed by an advisor, and never available to our own team.

🔒

Bank-Grade Encryption

AES-256 at rest and in transit, the standard applied by major financial institutions.

🏛️

SOC 2 Type II Certified

Independently audited for security, availability and data integrity. Documentation on request.

👁️

Zero-Knowledge Architecture

No SmartHeritance employee can read a client record. Privacy is structural, not procedural.

⚙️

Condition-Based Release

Records are released only once a client's predefined conditions are verified.

For compliance and legal teams: SmartHeritance is a client-owned record, not a custodial, advisory or firm recordkeeping system. We do not hold assets, execute transactions or provide advice. Advisor visibility exists only where a client explicitly grants it.

Request Compliance Documentation
Partner With Us

Bring the complete picture into your practice.

SmartHeritance works with independent RIAs, advisors licensed through broker-dealers, credit unions and community institutions. Describe how the book is structured and we will scope the appropriate pilot.

Firm-sponsored, client-paid and revenue-share models available

Runs alongside your existing technology, not through it

Deploys in days, outside any enrolment calendar

Request a pilot

We will walk you through the client experience, the advisor view, and how the pilot is measured.

Contact Us